ESOP advisory
ESOP Advisory, From Feasibility to Exit
We advise owners selling to an employee stock ownership plan, and companies selling or ending one.
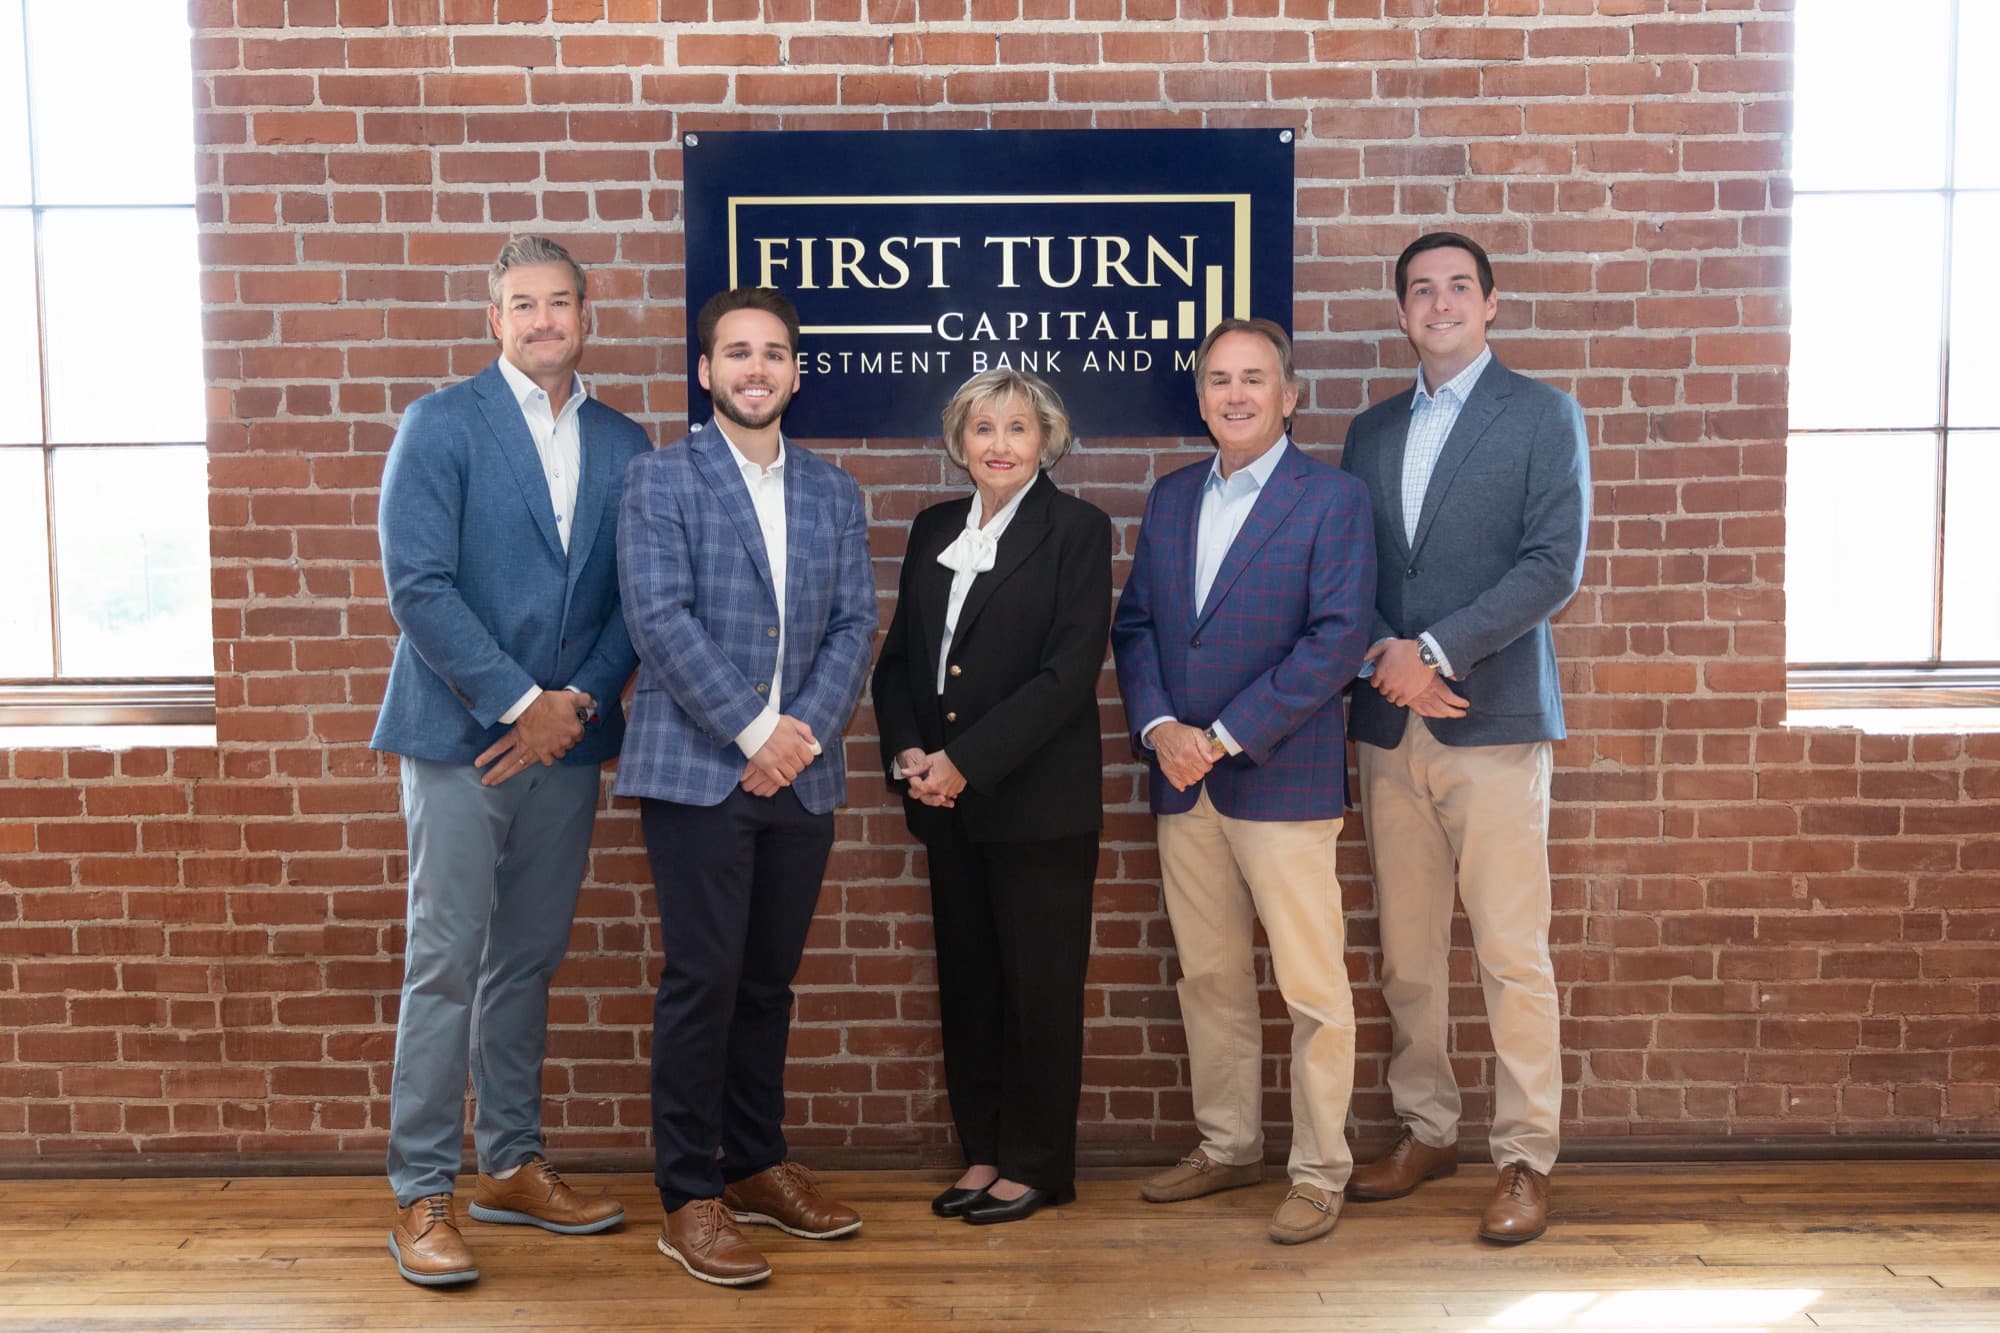
Left to right: Chad Godwin, Caleb Corbitt, Beverly Johnson, Doug Franklin, and Gray Katigan.
What an ESOP is and how a sale to one works
An employee stock ownership plan, or ESOP, is a qualified retirement plan that holds company stock in a trust for the employees. When an owner sells to an ESOP, the trust buys the shares, the company keeps its name, location, and management, and the employees build ownership over time without paying for it out of pocket.
The purchase is usually financed with a bank loan, company cash, and a note from the selling owner, which the company repays from its earnings over several years. That makes an ESOP a fit for companies with steady cash flow and for owners who are willing to be paid over time.
An ESOP is one exit among several. For some owners it fits better than a sale to an outside buyer because of taxes and legacy. For others, the price, the payout timing, or the company's debt capacity points to a different path. We help owners compare them before anyone commits.
Is an ESOP a fit?
A feasibility study answers that before the owner spends money on a transaction.
Financing capacity
Whether the company's cash flow can carry the acquisition debt and still fund operations and growth.
Repurchase obligation
The cash the company will need over the years to buy back shares from employees who retire or leave.
Owner goals
How much to sell now, how much cash at closing versus over time, and the role the owner wants afterward.
Tax structure
Whether the company is a C corporation or an S corporation, and what that means for the seller and the company.
Selling to an ESOP
The structure decides how and when the owner gets paid.
Financing
Senior bank debt, company cash, and a seller note are combined to fund the purchase. We arrange the bank financing and negotiate the seller note.
A full or partial sale
An owner can sell part of the company to the ESOP now and the rest later, or sell all of it in one transaction.
The Section 1042 rollover
Owners of C corporations who meet its requirements can defer capital gains tax on the sale by reinvesting the proceeds in qualified replacement property, such as stocks and bonds of U.S. operating companies. For S corporation sales after 2027, a limited part of the sale proceeds qualifies too. The rules are specific, and your tax advisor confirms whether you qualify.
Life after closing
Management usually stays, and many sellers stay engaged through a transition period while the company repays the debt.
Who sits at the table
An ESOP sale has more parties than most deals, and each represents someone different.
The company and the selling owners
This is our side. We advise the company and the sellers on structure, price, financing, and terms.
The ESOP trustee
The trustee acts for the employees who will own the shares, and it brings its own independent financial advisor and appraiser to judge the price.
ESOP counsel
Attorneys who draft the plan and the transaction documents and keep the deal within retirement plan and tax rules.
Lenders and administrators
The bank funding the purchase, and the plan administrator who keeps employee accounts after closing.
Selling or ending an ESOP company
ESOP companies are sold too. A board may decide that a sale to an outside buyer serves the participants better, or that the plan has done its job.
Selling the company
A sale to a strategic or financial buyer, run as a competitive process. The trustee decides whether the price and terms serve the participants, and on a merger or a sale of substantially all assets, participants direct the vote on their shares.
Terminating the plan
The company buys back the trust's shares and the plan is wound down, with participants paid out under the plan's rules.
A partial redemption
The company buys back part of the trust's stake to reset ownership or bring in a new owner.
How an ESOP sale runs
An ESOP sale runs in the stages below. The pace depends mostly on the feasibility study, the trustee negotiation, and the financing.
Feasibility
Financing capacity, repurchase obligation, tax structure, and the owner's goals, tested before any commitment.
Design
How much to sell, how to finance it, and how the plan will work for employees.
Valuation and negotiation
The trustee's appraiser values the shares, and we negotiate price and terms with the trustee for the sellers.
Financing
Bank financing arranged and the seller note terms set.
Closing
Documents signed, the trust buys the shares, and the money moves.
After closing
The trustee's annual independent valuation, plan administration, and planning for future share repurchases.
Who it fits
Owners who want to reward the employees who built the company and keep its name, location, and culture in place, with a company whose cash flow can carry the acquisition debt.
Owners who want the most cash at closing, or companies that cannot carry the debt, are often better served by a sale to an outside buyer. We lay that comparison side by side.
Industries we serve
Many ESOP companies are in the same industrial and blue-collar fields we serve on the sell side.
Aggregates & Quarries
Sell-side M&A advisory for owners of crushed stone quarries, sand and gravel pits, and construction aggregates operations.
Aggregates & Quarries M&A
Steel Fabrication & Erection
Sell-side M&A advisory for owners of structural steel fabricators, miscellaneous metals shops, steel erectors, and bridge fabricators.
Steel Fabrication & Erection M&A
Paving & Asphalt
Sell-side M&A advisory for owners of asphalt paving contractors, hot mix asphalt plants, and highway and street construction companies.
Paving & Asphalt M&A
Construction
Sell-side M&A advisory for owners of general contracting, heavy civil, and specialty trade contracting companies.
Construction M&A
Oilfield Services
Sell-side M&A advisory for owners of oilfield services and energy services companies, including well services, water, rental tools, and production services.
Oilfield Services M&A
Manufacturing
Sell-side M&A advisory for owners of manufacturing companies, including machine shops, metal fabrication, machinery, and other industrial producers.
Manufacturing M&A
Reading on ESOPs
- ESOP advisory: a business owner's guide
How ESOP transactions work from start to finish.
- The ESOP feasibility study
What it covers and why it comes first.
- ESOP or strategic sale
How the two exits compare.
- The Section 1042 rollover
Tax deferral for C corporation owners.
- Terminating an ESOP
Three exit paths for ESOP companies.
- The ESOP as a capital structure tool
Uses beyond the owner's exit.
Questions owners ask about ESOPs
What is an ESOP, and how does selling to one work?
An ESOP is a qualified retirement plan that holds company stock in a trust for employees. In a sale, the trust buys the owner's shares, usually with a bank loan, company cash, and a seller note that the company repays from earnings over several years. The company keeps its name and management, and employees build ownership over time.
Is my company a good fit for an ESOP?
An ESOP works best for a profitable company with steady cash flow, a management team that can run it without the owner, and an owner willing to be paid partly over time. A feasibility study tests the financing, the future cost of buying back employee shares, and the tax structure before you commit.
What is a Section 1042 rollover?
It is a provision of the tax code that lets owners of C corporations defer capital gains tax when they sell stock to an ESOP and reinvest the proceeds in qualified replacement property, such as stocks and bonds of U.S. operating companies. For S corporation sales after 2027, a limited part of the sale proceeds qualifies too. The ownership, holding period, and reinvestment rules are specific, so your tax advisor confirms whether a sale qualifies before you rely on it.
Whose side are you on in an ESOP sale?
We advise the company and the selling owners. The ESOP trustee acts for the employees and hires its own independent financial advisor and appraiser to judge whether the price is fair to the plan. Keeping those roles separate is how the transaction holds up under the rules that govern retirement plans.
Can an ESOP-owned company be sold?
Yes. An ESOP company can be sold to a strategic or financial buyer, usually through a competitive process. The trustee decides whether the price and terms serve the participants, and on a merger or a sale of substantially all assets, participants direct the vote on their shares. The proceeds pass through the plan to employee accounts. A company can also buy back the trust's shares and end the plan.
How does an ESOP termination work?
The board decides to end the plan, the company buys back the shares the trust holds at a price the trustee accepts, and participant accounts are paid out under the plan's rules, usually in cash or as a rollover to an IRA. It is a transaction, with valuation, financing, and fiduciary review, not just paperwork.
How long does an ESOP sale take?
Feasibility comes first, then valuation, structuring, the trustee negotiation, and financing, which take most of the time. The pace depends on how ready the company is and how quickly the bank and the trustee work through their reviews. An entity conversion or a contested valuation can stretch the timeline further.